European and UK businesses are grappling with one of the most volatile operating environments in modern history. They are coming under intense financial pressure arising from high labour and energy costs, as well as tariff wars and geopolitical tensions that are squeezing profit margins and straining supply chains. The lingering effects of the cost-of-living crisis are also rippling across the continent, with weak consumer demand providing business decision-makers with more pain.
Europe’s businesses are relied upon as engines of growth, job creation and economic resilience – yet they are facing this difficult climate with slower, more manual financial services. They consistently report a customer experience that falls far short of what’s on offer to their consumer counterparts.
This report drills down into the variance between consumer and business services in areas including banking, lending and insurance, and specifically where businesses feel services are missing the mark. The gap is extensive; it spans speed and administrative burdens, access to credit and cost, the pace of innovation, business size and ultimately the extent to which providers actually understand the businesses they seek to serve.
Doing business in Europe
Home to around 33.5 million enterprises, the EU employs more than 164 million people and generates €38.7 trillion in net turnover. The EU remains the world’s largest trading bloc. Despite geopolitical tensions and other external cost pressures, the European business sector has also shown resilience.
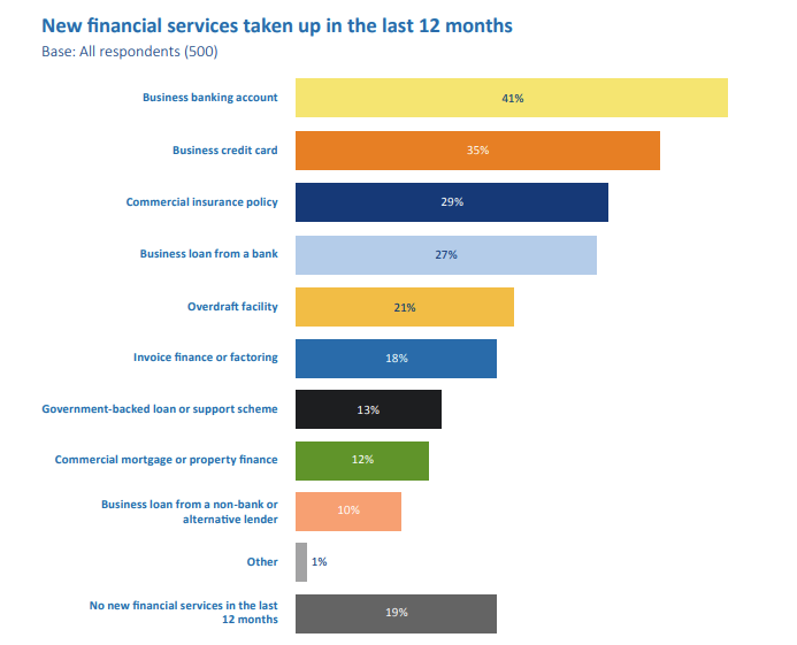
Financial providers have a huge role to play in supporting these new business owners, as well as established businesses, with working capital solutions and other financial services to support their growth. Our research reveals a growing appetite. Eight in ten (81%) European businesses have taken up at least one new financial product or service within the last year, with more than a quarter (27%) requesting a business loan from their bank.
Understanding friction in the UK
UK businesses report the least friction of any market surveyed. They are the least likely to say that business eligibility is harder to meet than personal (39% against 52% overall), that a lack of innovation is stifling growth (28% against 41%) or that the wider economic climate is reducing their customers’ demand (54% against 65%). Yet they are also among the most willing to move between providers.
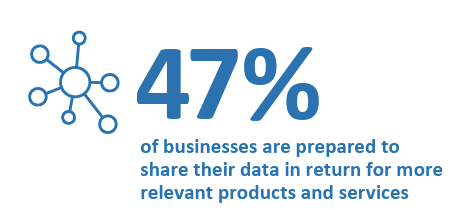
Two-thirds (67%) would share more data in return for lower insurance premiums, which is the highest of the five markets surveyed. A similar proportion (68%) regularly review or change insurance provider, while three in ten (27%) cite flexible, tailored products as a major consideration when selecting a financial provider. Loyalty is very much a secondary concern in a market where businesses are focused on getting the right products and services to meet their evolving needs.
Download the report to discover what businesses really expect from banks, lenders and insurers.